Separate Cargo Cover from Carrier Liability
An overseas shipment can arrive damaged even when every supplier has met its production commitments. Cargo insurance protects an insured financial interest against covered physical loss or damage, subject to the policy wording. Carrier liability is a different mechanism, governed by transport contracts and applicable law. It may depend on proving responsibility and can be restricted by package or weight limits.
Do not treat a freight quote that includes a liability provision as proof of adequate cargo cover. Ask whether an actual cargo policy exists, who is insured and which insurer handles claims. Review the deductible, territorial scope and exclusions rather than relying on a description such as fully insured. The commercial objective is recoverable protection, not simply a certificate attached to the shipping documents.
Map Risk Transfer Before Buying Insurance
Start with the sale contract and its exact Incoterms rule, named place and version. These terms help identify when transit risk moves between seller and buyer, but they do not determine ownership or every insurance question. Your financial interest may also depend on payment arrangements and contractual obligations. Ask a broker to align the insured parties and covered interests with those arrangements.
Under Incoterms 2020, CIF and CIP require the seller to procure specified insurance for the buyer’s risk, while most other rules impose no such obligation. CIF generally calls for minimum Institute Cargo Clauses (C) or equivalent cover, whereas CIP generally calls for Clauses (A) or equivalent, subject to agreed variations. Neither label guarantees protection for every commodity or route. Obtain the actual terms and evidence that you can claim under them.
Compare Perils, Exclusions and Product Sensitivities
Institute Cargo Clauses (A) generally cover all risks of physical loss or damage except excluded causes; they do not insure every possible business setback. Clauses (B) and (C) provide narrower named-perils cover. Delay, ordinary leakage, inherent vice and inadequate packing can create major gaps, depending on the wording and circumstances. A late seasonal delivery may therefore produce a trading loss without a covered cargo claim.
Match the discussion to the goods rather than choosing a clause solely by price. Electronics may need attention to theft and moisture, while food can require temperature-related extensions and suitable monitoring. War and strikes cover commonly require separate consideration, and sanctions restrictions may affect availability or payment. Ask the broker to explain relevant exclusions using your packaging, storage conditions and shipment itinerary, not a generic product description.
Set the Insured Value and Deductible Deliberately
The invoice amount is only the starting point for deciding the sum insured. Freight, insurance costs and an agreed uplift may be included under the valuation clause, but the policy must state the basis. CIF and CIP ordinarily require insurance of at least 110 percent of the contract price when obtainable under their insurance provisions. That convention is not a promise to reimburse every consequential loss or your actual resale margin.
Example
Illustrative valuation comparison
All numbers in this scenario are illustrative. A buyer ships goods invoiced at $40,000 and pays $4,000 freight; an agreed policy basis of invoice plus freight plus 10 percent produces $48,400 of insured value. If instead the wording provides 110 percent of the goods invoice alone, the figure is $44,000. The buyer asks the broker to confirm the correct basis and how a $1,000 deductible would apply to a partial loss.
Check whether deductibles apply per shipment, occurrence, package or another defined unit. Compare them against likely repair bills and smaller recurring losses, not only a total-loss scenario. Also confirm any single-conveyance, location or accumulation limits when multiple orders share one vessel or warehouse. Adequate annual turnover declarations do not automatically remove a restrictive per-location limit.
Define the Entire Route and Coverage Period
International movements often combine factory collection, consolidation, port handling, ocean or air carriage and final delivery. Warehouse-to-warehouse language has defined attachment and termination provisions; it does not mean unlimited storage protection wherever goods happen to sit. Obtain clarity on intermediate warehouses, transshipment, customs holds and changes of destination. A route change should trigger a coverage check before the cargo is diverted.
- Describe the origin, destination, transport modes and expected storage periods in the insurance submission, including any consolidation or repacking points.
- Ask when cover attaches and terminates, and which time limits apply after discharge or during storage outside the ordinary course of transit.
- Confirm who must notify the insurer about delays, deviations, vessel changes or extensions, and retain written acceptance of material changes.
Choose a single-shipment policy for occasional movements or discuss open cover for recurring trade. Open cover can simplify administration, but declaration duties, eligible goods and limits still matter. Assign responsibility for declarations so that a booking is not mistaken for completed insurance placement. Keep evidence of acceptance accessible to both logistics and finance teams.
Prepare Packing and Shipment Evidence Early
Insurance cannot substitute for transport-ready packaging and clear handover records. Ask the supplier to document carton specifications, internal protection, pallet condition and any moisture controls that the product requires. Photographs should show identifiable goods, packing stages and the sealed shipment where practicable. They support a factual account but do not prove that every policy condition has been met.
Before dispatch, confirm the insurance file contains
- ✓Policy or certificate, applicable clauses, endorsements, insured parties and a verified claims contact.
- ✓Commercial invoice, packing list, transport booking and agreed valuation basis.
- ✓Product description, packaging evidence and any required temperature or handling instructions.
- ✓Shipment identifiers, route, expected dates and proof of any required declarations.
- ✓A receiving procedure covering exceptions, photographs, surveys and urgent notices.
Source & Brand can coordinate supplier information, packaging requirements and logistics handoffs as part of sourcing support. It does not own factories, issue inspection certificates or act as a customs broker. Coverage advice, binding confirmation and claims interpretation should come from the insurer or an appropriately qualified insurance adviser. Keep each party’s responsibility explicit instead of assuming coordination transfers liability.
Respond to Damage Without Prejudicing Recovery
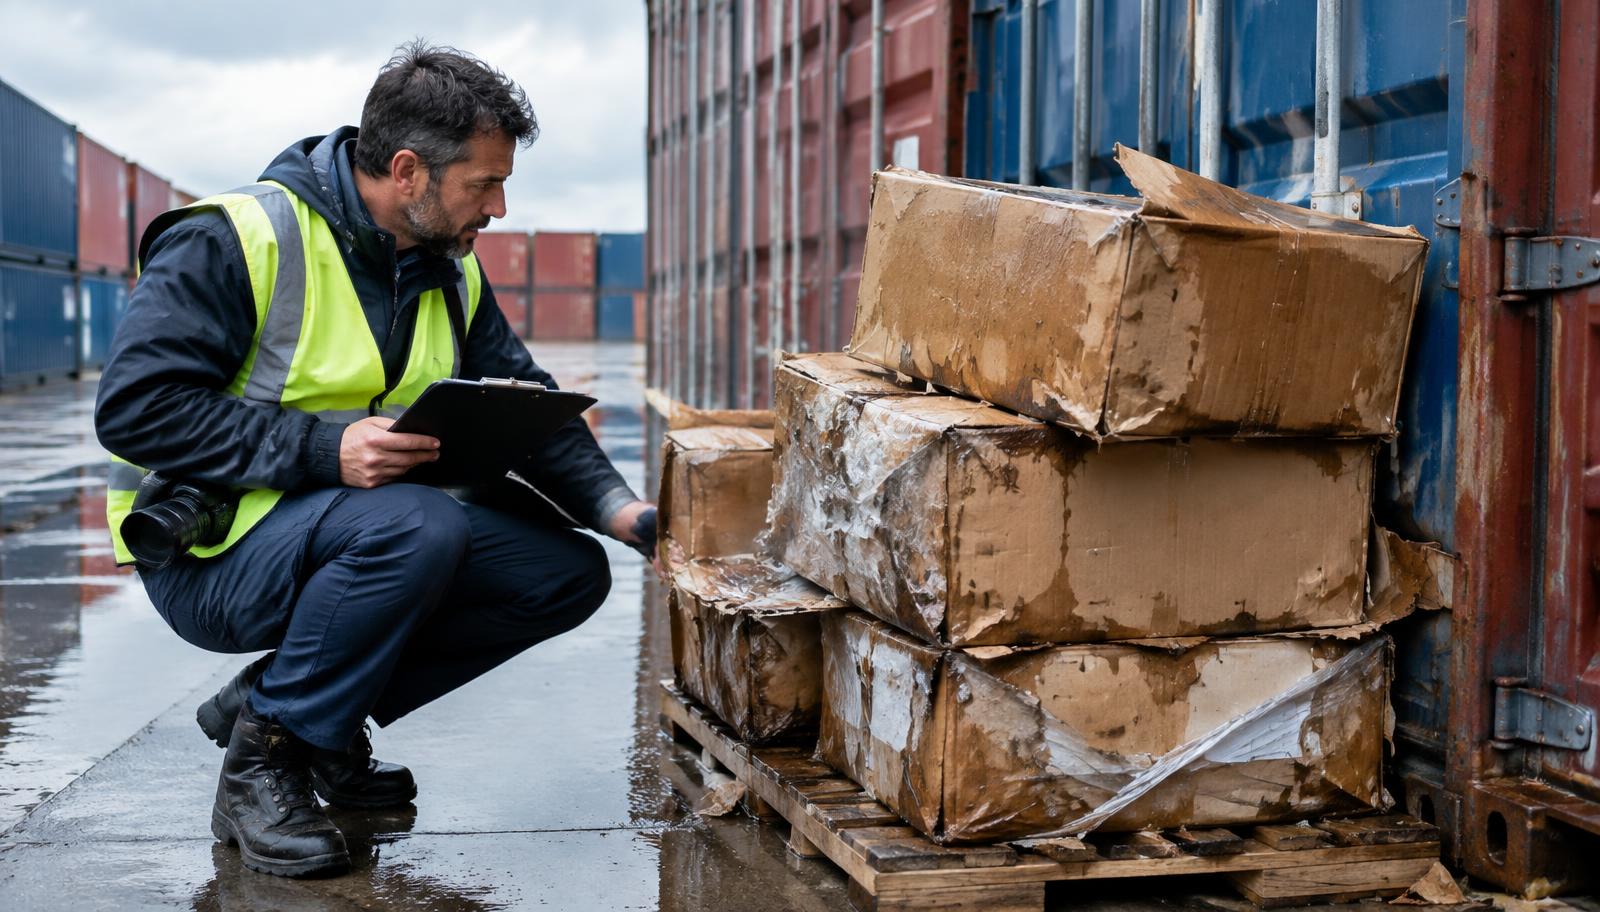
Give receiving teams written instructions before arrival, especially when an external warehouse signs for deliveries. Record visible damage or shortages on delivery documents rather than issuing an unqualified receipt where exceptions are apparent. Photograph the packaging, seals, labels and affected goods, and notify the insurer promptly under the policy. Hidden damage should also be reported as soon as discovered, with its discovery circumstances recorded.
- Protect people and take reasonable steps to prevent further damage, following safety requirements and obtaining insurer guidance where practicable.
- Preserve packaging and damaged goods, request any required survey, and avoid disposal or major repairs without appropriate authorization.
- Notify carriers and other potentially responsible parties within applicable deadlines, preserving recovery rights without admitting liability or agreeing a settlement.
- Submit invoices, transport documents, survey findings and a quantified loss calculation, then track requests and responses in one claim file.
Compare Proposals on Recoverability, Not Premium Alone
Ask each provider to quote against the same cargo description, route, valuation and deductible. Compare exclusions, claims assistance, survey arrangements, governing law and how claims are paid to the intended beneficiary. Check insurer identity and authorized distribution channels rather than relying on a forwarded certificate. Where wording is unclear, request a written explanation or endorsement before shipment.
Review the arrangement whenever products, suppliers, routes or sales terms change. A policy designed for dry packaged components may not suit fragile assembled products or temperature-sensitive goods. Use claim experience to improve packaging and handling, while keeping prevention work separate from coverage decisions. The best renewal discussion combines operational evidence with a precise account of the financial exposure you need insured.
Ask the insurer or broker to explain the claim procedure using your actual route and cargo type. Confirm when coverage starts and ends, the insured value, deductible, exclusions and required packing conditions. Retain invoices, transport documents and photographs of packing before shipment. On delivery, document visible damage promptly and follow the policy’s notification requirements rather than waiting for the supplier to investigate. Carrier liability and cargo insurance are different arrangements; a freight quote that mentions insurance should still identify the actual policy terms and who can submit a claim.
Frequently asked questions
Is cargo insurance legally mandatory?
There is no universal rule requiring every international shipment to carry cargo insurance. Particular contracts, finance arrangements or local requirements may require it, so check the transaction rather than assuming a global answer.
Does all-risks cover include delivery delays?
Not automatically; standard cargo cover commonly excludes loss caused by delay. Ask about specific additional protection if delay-related exposure is commercially important.
Can the buyer rely on insurance arranged by the seller?
Only after checking the actual cover, insured interest and ability to claim. A seller’s insurance obligation under the chosen term may provide less protection than the buyer wants.
Who should arrange a damage survey?
Contact the insurer or its designated claims representative promptly for instructions. Do not assume that a warehouse report replaces a survey required by the policy.
Does a higher insured value guarantee a larger payout?
No; settlement still depends on the covered loss, valuation provisions, limits and deductible. Overstating value does not turn an excluded event into an insured claim.
Key takeaway
Buy cargo insurance around the actual risk transfer, product vulnerabilities and complete transit route. Confirm the wording before dispatch and prepare receiving teams to preserve evidence and recovery rights.